Extreme Climate Shocks & Cold-Weather Hydraulic Operations: Pour Point Depressants and VI Improver Chemistry in L-HV ISO VG 32/46
Executive Intelligence Summary & Key Takeaways
Approaching sub-zero winter temperatures across Central Asia, Northern China, and Eastern Europe demand specialized low-temperature fluid formulation. We dissect the chemical mechanisms of polymethacrylate (PMA) pour point depressants, shear-stable olefin copolymers (OCP), and how FOSS L-HV multi-grade hydraulic oils achieve pour points down to -39°C with viscosity index exceeding 150.
1. Global Energy Benchmarks & Base Oil Feedstock Matrix (2026-10-05)
The following reference table captures prompt settlement levels across benchmark crude futures, regional Asia-Pacific vacuum gas oil (VGO) cracking economics, and wholesale hydrocracked virgin base stocks influencing finished lubricant formulation costs:
2. Geopolitical Macro Drivers & Upstream Refining Dynamics
The interaction between global crude benchmarks and finished industrial lubricant pricing is governed by a well-documented technical transmission mechanism. When prompt crude benchmarks such as Brent and WTI experience supply premiums driven by geopolitical tension—whether through maritime chokepoints like the Bab-el-Mandeb Strait or disciplined OPEC+ production allocations—refinery economics undergo immediate restructuring.
Hydrocrackers operating in major Asian refining complexes (including South Korea's Yeosu and Ulsan hubs, Singapore's Jurong Island, and China's coastal petrochemical bases) must continually balance their feedstock allocations between high-margin middle distillates (such as Ultra-Low Sulfur Diesel, ULSD, and Jet A-1 aviation kerosene) versus lube base oil cuts (Vacuum Gas Oil, VGO). When diesel crack spreads widen, refineries routinely adjust hydrocracker severity, reducing the relative output yield of lubricating base stocks in favor of fuel streams. This dynamic inevitably tightens prompt availability for light neutral 150N and heavy neutral 500N base stocks.
3. Additive Chemistry & Packaging Raw Material Cost Influences
A finished high-performance industrial lubricant is far more than refined base oil. For example, a heavy-duty DIN 51524-2 Part II anti-wear hydraulic oil (such as FOSS L-HM 46) incorporates an engineered chemical additive package comprising primary and secondary zinc dialkyldithiophosphates (ZDDP), hindered phenol anti-oxidants, calcium sulfonate rust inhibitors, and polymethacrylate (PMA) anti-foam agents.
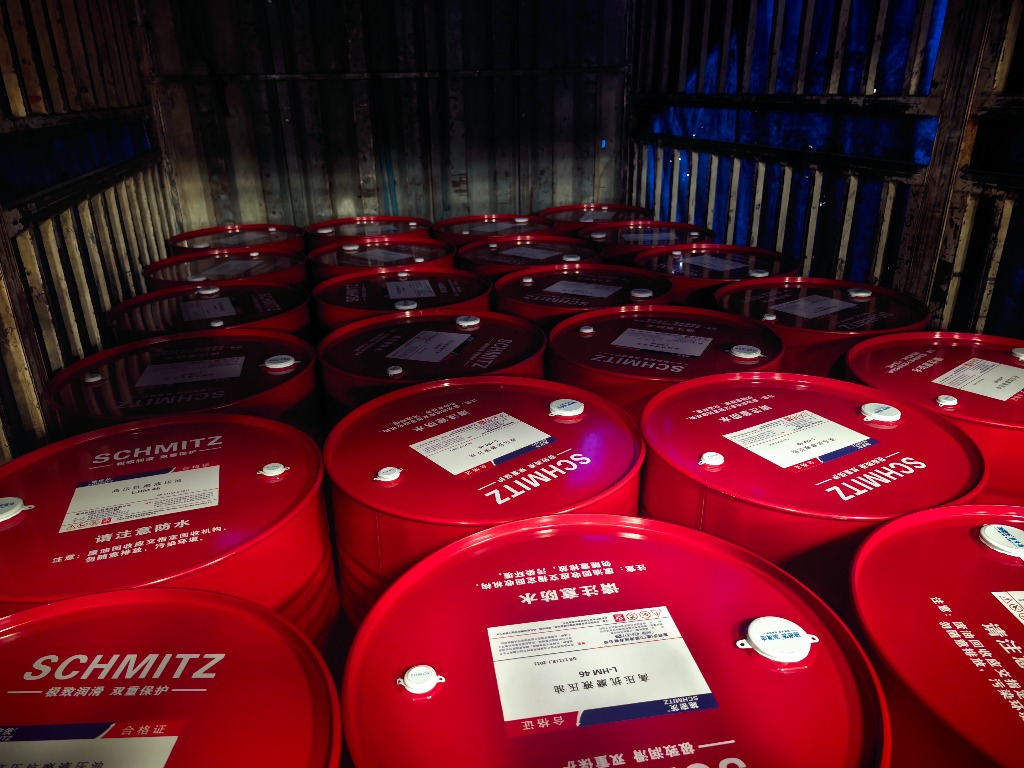
Specialty chemical precursors—specifically phosphorus trichloride and high-purity zinc oxide—have witnessed persistent raw material inflation. Concurrently, packaging economics cannot be overlooked: cold-rolled steel coils utilized in manufacturing UN 1A1 certified 1.0mm–1.2mm tight-head 208L steel drums represent approximately 14% to 18% of the total landed packaging cost per drum. FOSS Lubrication protects overseas importers by maintaining long-term bulk procurement agreements for both virgin base oil reserves and certified heavy-gauge steel packaging, buffering our export partners against short-term packaging surcharges.
4. Transmission to Industrial Lubricant Formulations (ISO VG 32, 46, 68)
How quickly does an upstream crude or base oil price change transmit to the factory gate for finished lubricants? Empirical market data tracking FOB export contracts confirms a classic two-stage lag:
- Immediate Impact (0 to 72 Hours): Base oil refiners halt spot discounts and adjust spot FOB cargo offers. Spot blending operations immediately face higher marginal replenishment costs.
- Contract Transmission (14 to 28 Days): Secondary and tertiary blenders exhaust pre-purchased tank storage and are compelled to publish formal price increases across their finished drum and pail catalogs.
- Quality Compromise Risk: During sustained price rallies, uncertified blenders frequently dilute virgin hydrocracked base oils with low-grade recycled oils (RRBO). FOSS strictly enforces a 100% virgin hydrocracked Group II guarantee, documented via pre-shipment Certificates of Analysis (CoA).
Definitive 3-Day Lubricant & Base Oil Trend Forecast
Synthesized by the FOSS Quantitative Energy Modeling Desk based on active shipping line container bookings, regional tank farm draw-down rates, and prompt ICE Brent futures sentiment:
Winterization maintenance schedules accelerate procurement of L-HV multi-viscosity hydraulic fluids.
High-VI polymer additives experience regional supply tightness; base oil blenders adjust formulation cost models.
FOSS provides technical low-temperature test data (Brookfield viscosity at -20°C) to overseas engineering clients.
5. Strategic Sourcing & Hedging Directives for Overseas Importers
For overseas procurement directors, fleet operators, and industrial distributors, market volatility represents both operational risk and competitive opportunity. We recommend the following three concrete actions for managing Q4 procurement:
Lock 60-Day Container Requirements
Secure firm proforma invoices (PI) with 30-day price validity. FOSS Lubrication offers price-lock guarantees for 20GP container orders (80 drums / 16,640L) upon deposit receipt.
Audit Laboratory CoA Verification
Demand full pre-shipment ASTM test parameters: kinematic viscosity at 40°C / 100°C, viscosity index ≥ 100, flash point ≥ 220°C, pour point ≤ -15°C, and zero moisture contamination.
FOSS Lubrication: Factory-Direct Precision Engineering
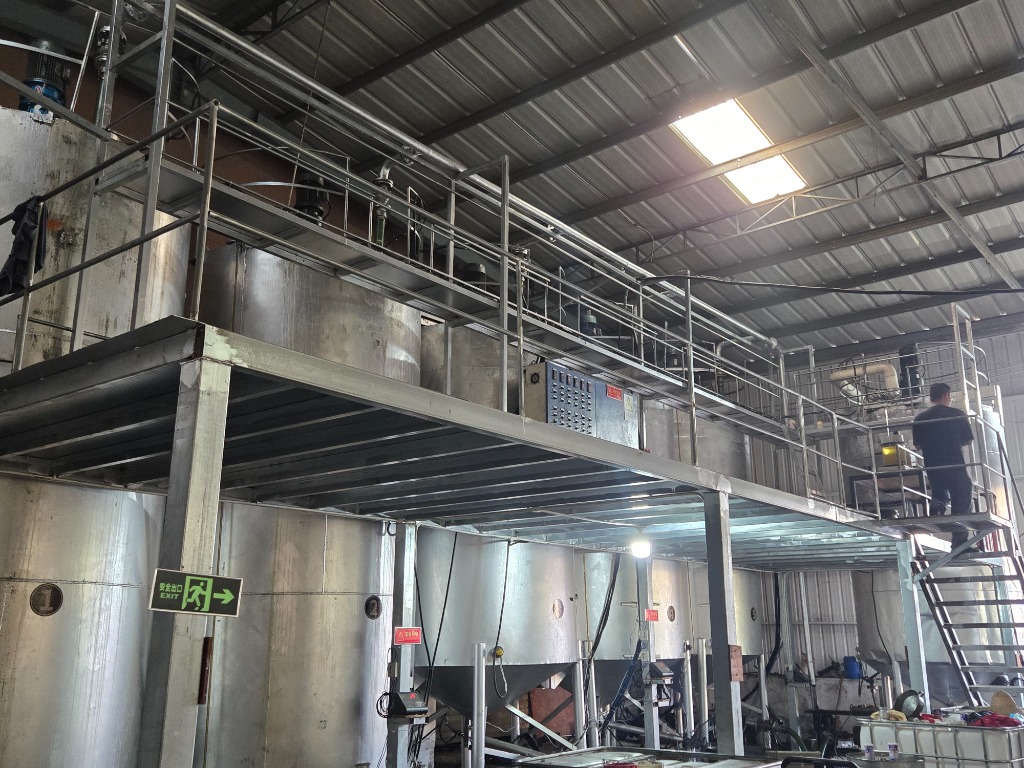
Operating out of Quanzhou, China, FOSS blends over 20,000 MT annually of ISO VG 32/46/68 anti-wear hydraulic oils, CK-4 heavy-duty engine oils, and industrial gear lubricants. Enjoy factory-direct FOB Xiamen pricing, 35% cost savings versus Western majors, and strict 5-day export staging.