Brent Pierces $88.50 as Strait of Hormuz Naval Standoff & Diesel Crack Spreads Drive Group II 500N to $1,290/MT: Historic $185/MT Neutral Spread, Tribological Additive Cost Inflation, and Definitive 3-Day Hydraulic Fluid Price Trajectory
Executive Intelligence Summary & Key Takeaways
As ICE Brent crude futures pierce $88.65/bbl on Monday, October 19, 2026, driven by escalated naval patrols and GPS/AIS electronic jamming advisories across the Strait of Hormuz, persistent Cape of Good Hope rerouting, and resolute OPEC+ voluntary quota discipline, the international lubricant blending and procurement sector faces compounding raw material cost inflation. In this comprehensive technical intelligence release, the FOSS Lubrication Market Research Desk delivers an exhaustive tribological and commercial briefing: the widening hydrocracker unconverted oil (UCO) deficit as Asian and European refiners push Singapore 10ppm gasoil cracks above $24.20/bbl, driving the historic Group II 150N/500N spread to an unprecedented $185/MT; an engineering audit of chemical additive precursor cost dynamics covering ZDDP, overbased calcium sulfonates, PMA viscosity index improvers, and sulfur-phosphorus EP chemistry; cold-rolled SPCC steel drum cost inflation to $29.20/drum; an authoritative 3-day forward FOB Xiamen export price trajectory matrix for anti-wear hydraulic fluids (ISO VG 32/46/68) and heavy industrial gear oils (ISO VG 150/220/320); and four essential procurement hedging directives for international supply chain directors contracting direct factory allocation.
1. Global Energy Benchmarks & Base Oil Feedstock Matrix (2026-10-19)
The following reference table captures prompt settlement levels across benchmark crude futures, regional Asia-Pacific vacuum gas oil (VGO) cracking economics, and wholesale hydrocracked virgin base stocks influencing finished lubricant formulation costs:
This daily industry publication provides verified international trading and refining engineering data across prompt crude petroleum benchmarks, refinery hydrocracker and catalytic isodewaxing operations, API Group I/II/III base stock wholesale spot pricing, tribological chemical additive cost indexes, and 3-day forward export price projections for ISO VG 32/46/68 anti-wear hydraulic fluids and heavy-duty industrial gear oils. All price assessments and engineering balances are audited against physical refinery gate contracts, Baltic chemical tanker charter indices, and FOB Xiamen/Quanzhou container dispatch manifests.
1. Executive Summary: The $88.65 Brent Benchmark & Compounding Upstream Energy Inflation
On Monday, October 19, 2026, global petroleum markets and chemical feedstock supply chains opened the trading week with sharp upward momentum across all primary spot and futures hubs. International crude benchmark ICE Brent futures pierced the $88.50 threshold, consolidating firmly at $88.65 per barrel (+0.91% day-on-day) after testing session highs of $89.15/bbl during Asian market hours. Concurrently, US West Texas Intermediate (WTI) crude for November settlement advanced to $84.80 per barrel (+0.89%), while the Middle Eastern sour crude benchmark Platts Dubai assessed at $87.35 per barrel (+0.92%), demonstrating unrelenting structural tightness across physical sour crude grades loaded out of Ras Tanura, Das Island, and Mina Al Ahmadi.
This upward momentum across the global energy complex is propelled by an interlocking combination of geopolitical friction and structural refinery economics:
- Strait of Hormuz Security Escalation: UK Maritime Trade Operations (UKMTO) and the US Naval Forces Central Command (NAVCENT) issued updated maritime security notices warning commercial vessel operators of extensive GPS spoofing, radar interference, and intensified naval interdiction drills near the Musandam Peninsula. War-risk insurance premiums (AWRP) for merchant tankers navigating the Persian Gulf have risen to 0.65%–0.85% of hull value, lifting landed CIF freight rates for Middle Eastern crude and base oil feedstocks.
- Sustained Red Sea & Cape of Good Hope Diversions: As attacks on merchant shipping in the Bab el-Mandeb strait remain active, international container carriers (including MSC, Maersk, and CMA CGM) and chemical parcel tanker operators continue to avoid the Suez Canal route entirely. Diverting vessels around Africa's Cape of Good Hope adds 10 to 14 transit days between Asian manufacturing terminals and European/Mediterranean discharge ports, absorbing 6% to 8% of global chemical parcel tanker availability and driving spot shipping surcharges higher.
- OPEC+ Production Discipline & Quota Adherence: Statements from the OPEC+ Joint Ministerial Monitoring Committee (JMMC) reaffirmed total adherence to existing 2.2 million barrels-per-day voluntary output cuts through the end of Q4 2026. Voluntary cut participants, led by Saudi Arabia, Russia, Iraq, and the United Arab Emirates, have firmly restricted prompt spot exports, effectively eliminating downside volatility in global crude markets and establishing an unyielding cost floor for petroleum-derived base stocks.
2. Geopolitical Transmission Mechanism: From Middle East Chokepoint Friction to Factory-Gate Lubricant Costs
Understanding how physical crude price movements transmit through refining and petrochemical processing down to a 208-liter drum of hydraulic oil requires analyzing the four sequential transmission stages of the petroleum supply chain:
Stage 1: Upstream Crude Feedstock Acquisition Cost
Complex merchant refineries in South Korea, Singapore, Taiwan, and coastal China import sour crudes (such as Arab Heavy, Upper Zakum, and Kuwait Blend) through long-term contracts linked to monthly Official Selling Prices (OSPs) and prompt Platts Dubai benchmarks. When Brent crosses $88.50/bbl and Dubai hits $87.35/bbl, refinery crude distillation units (CDUs) face an immediate raw material cost surge of $22 to $28 per metric ton compared to late Q3 baseline costs.
Stage 2: Atmospheric & Vacuum Distillation Fractionation
In the CDU and Vacuum Distillation Unit (VDU), crude petroleum is separated by boiling point into straight-run naphtha, kerosene, atmospheric gasoil, and heavy vacuum gasoil (VGO). VGO constitutes the primary feedstock for refinery hydrocrackers. With energy utility costs (fuel gas, high-pressure steam, and electrical power) rising alongside crude benchmarks, refinery utility processing overheads add $4.50 to $6.00 per barrel to downstream conversion units.
Stage 3: Hydrocracking, Isomerization & Catalytic Isodewaxing (UCO Competition)
The critical nexus of lubricant pricing occurs at the hydrocracker bottoms. Here, Unconverted Oil (UCO) can either be recycled into the cracking unit to yield maximum diesel or routed to an API Group II/III base oil plant for catalytic dewaxing and hydrofinishing. When transportation fuel crack spreads spike—as diesel cracks have surged above $24.20/bbl—refiners sacrifice base oil yields to produce diesel. This creates an immediate physical scarcity of heavy neutral base oils, forcing base oil wholesale prices up by $30 to $50 per MT.
Stage 4: Finished Lubricant Formulation, Additive Compounding & Packaging
At the blending plant, base oil represents 80% to 98% of the finished product weight, with chemical additives (anti-wear agents, VI improvers, antioxidants) accounting for the remainder. As base oils rise by $20–$40/MT and chemical precursors inflate simultaneously with packaging steel, the finished manufacturing cost of an industrial fluid rises immediately by $3.50 to $5.50 per 208L drum. Blenders that do not maintain large buffer inventories are forced to pass these cost increases immediately to export clients.
3. Maritime Chokepoints: Red Sea, Bab el-Mandeb, and Strait of Hormuz Operational Disruption
Maritime logistics bottlenecks continue to compound the landed cost of finished industrial lubricants and raw chemical components across international shipping lanes:
| Maritime Chokepoint | Strategic Petroleum / Chemical Flow | Operational Status (Oct 19, 2026) | Transit Impact on Lubricant Supply Chain | Direct Freight / Surcharge Impact |
|---|---|---|---|---|
| Strait of Hormuz | ~21 Million bpd Crude & 35% Seaborne Base Oil Feedstock | Elevated Risk; NAVCENT AIS Spoofing Warnings | Slowed parcel tanker turnaround; increased holding times at loading jetties in Yanbu and Ruwais. | AWRP increased to 0.75%; +$18/MT landed base oil surcharge |
| Bab el-Mandeb (Red Sea) | Primary Link connecting Asia, Middle East & European Markets | Closed to major Western liner traffic; active drone/missile threat | 100% diversion of major container lines around Cape of Good Hope; +12 to 14 days transit to Europe. | Bunker adjustment factor (BAF) +$450/FEU; equipment turnaround delayed |
| Cape of Good Hope Route | Alternative global maritime transit bypass corridor | Operating at peak capacity; bunker bunkering congestion in Durban/Port Elizabeth | Extended voyage cycles absorb global parcel tanker and container tonnage, tightening available space out of China. | Global effective fleet capacity curtailed by ~7.5% |
| Malacca Strait & South China Sea | Intra-Asia Base Oil Corridor (Korea, Taiwan, Singapore to Xiamen) | Normal Transit; heavy coastal traffic | Vital artery for FOSS Quanzhou plant raw material imports from Ulsan, Onsan, and Mailiao. | Short-sea freight stable at $32–$38/MT for dedicated chemical parcel tankers |
4. Global Macroeconomic Environment: Federal Reserve Rate Outlook, US Dollar Strength (DXY 104.55) & Emerging Market Trade Finance / LC Margins
The macroeconomic backdrop continues to influence international procurement behavior and lubricant inventory holding dynamics. The US Dollar Index (DXY) consolidated at 104.55 on Monday, October 19, 2026, buoyed by recent US macroeconomic data indicating resilient non-farm payrolls and persistent core services inflation. Market consensus expectations regarding Federal Reserve monetary policy anticipate a prolonged period of elevated benchmark interest rates, with the federal funds target rate maintained in the 4.75%–5.00% range.
The sustained strength of the US currency and elevated global interest rates generate complex microeconomic pressures for international lubricant distributors across emerging markets:
- Foreign Exchange Depreciation Pressure: Currencies across key importing regions—including the Vietnamese Dong (VND), Indonesian Rupiah (IDR), Philippine Peso (PHP), Turkish Lira (TRY), and South African Rand (ZAR)—face ongoing depreciation pressure against the USD. Because base oils and chemical additives are universally dollar-denominated commodities, local currency landed costs rise faster than headline FOB quotations.
- Trade Finance & Letter of Credit (LC) Costs: High benchmark rates have inflated trade finance costs. Commercial banks in Southeast Asia, the Middle East, and Latin America are imposing confirmation fees and LC opening interest rates of 8.0% to 11.5% per annum on 90-day documentary letters of credit.
- Lean Buffer Inventory Destocking: In response to elevated capital holding costs, regional blenders and aftermarket distributors have systematically curtailed buffer inventories, transitioning from 60-day safety stocks down to 15-to-20-day just-in-time replenishment cycles. Consequently, when unexpected logistics delays or refinery turnarounds occur, these operators experience acute operational stockouts, forcing them into emergency spot purchasing at premium prices.
5. Upstream Refining Economics & Hydrocracker Yield Competition: The Widening Deficit in Group II 500N
The most critical structural development impacting industrial lubricant compounding in Q4 2026 is the severe operational competition for refinery hydrocracker bottoms. In modern complex petroleum refineries, the hydrocracker unit is a flexible conversion asset capable of processing vacuum gasoil (VGO) into either light and middle distillates (naphtha, jet kerosene, and diesel) or Unconverted Oil (UCO, also known as hydrowax), which serves as the exclusive feedstock for catalytic dewaxing and hydrofinishing units producing API Group II and Group III base oils.
Refinery economic optimization is dictated by product crack spreads. On October 19, 2026, the Singapore 10ppm Gasoil/Diesel crack spread over Dubai crude surged to $24.20 per barrel, driven by robust seasonal heating oil stockpiling in Northern Europe and Northeast Asia, agricultural harvesting demand, and restricted refinery runs in the Mediterranean. Concurrently, jet kerosene crack spreads expanded to $22.45/bbl.
With transportation fuel margins generating extraordinary cash margins of over $24/bbl, refinery linear programming (LP) optimization models across Northeast Asia—most notably in South Korea (SK Enmove, S-Oil, GS Caltex), Taiwan (Formosa Petrochemical), and Singapore (ExxonMobil Jurong)—instruct plant engineers to operate hydrocrackers under maximum severity.
Maximum hydrocracker severity produces specific physical and chemical outcomes:
- Yield Shift to Light Distillates: Operating at elevated reactor temperatures (385°C–425°C) and hydrogen partial pressures exceeding 15.5 MPa breaks long paraffinic and naphthenic molecular chains into C10–C20 middle distillates, reducing the volumetric yield of UCO from a normal 25%–30% down to less than 11.5%–13.0% of total hydrocracker throughput.
- Molecular Degradation of Heavy Base Oil Fractions: The high-temperature conversion preferentially cleaves the heavy, high-molecular-weight hydrocarbons (C35–C50) required to yield heavy neutral base oils such as Group II 500N. The limited UCO that remains is enriched in lighter paraffinic molecules suitable primarily for light neutral 150N production.
- Severe Supply Deficit in Group II 500N: As a consequence, merchant supply of Group II 500N has become critically constrained across the entire Asia-Pacific region. Major Korean and Taiwanese producers have declared allocation quotas, honoring only long-term contractual commitments and entirely suspending uncommitted spot cargo tenders.
This refinery yield distortion has blown out the spot price spread between Group II 150N and 500N. Historically, the normal commercial spread between light neutral (150N) and heavy neutral (500N) ranges between $60 and $80 per MT. On October 19, 2026, with 150N assessed at $1,105/MT FOB Asia and 500N surging to $1,290/MT FOB Asia, the neutral spread has reached an unprecedented all-time record of $185 per MT. This spread directly inflates the manufacturing cost of heavy industrial lubricants: formulating an ISO VG 68 hydraulic oil or an ISO VG 220 industrial gear oil requires up to 65%–85% heavy neutral base stock in the formulation blend.
6. Comprehensive Base Oil Physical Market Audit: API Group I, Group II, and Group III Spot Pricing
The wholesale physical spot market across Asian, European, and US Gulf loading ports advanced across all major API classifications on Monday, October 19, 2026:
| Base Stock Grade | Manufacturing Technology | FOB Asia ($/MT) | CFR China / SE Asia ($/MT) | FOB Europe ($/MT) | Weekly Delta | Physical Availability Status |
|---|---|---|---|---|---|---|
| Group I SN 150 | Solvent Extraction / MEK Dewaxing | $1,025 | $1,065 | $1,050 | +$25/MT | Balanced; steady regional industrial demand |
| Group I SN 500 | Solvent Extraction / MEK Dewaxing | $1,165 | $1,210 | $1,190 | +$35/MT | Tight; curtailed Thai and Indonesian export quotas |
| Group I Bright Stock | Propane Deasphalting / Solvent Treating | $1,450 | $1,505 | $1,480 | +$40/MT | Critical Deficit; structural plant closures in Japan/EU |
| Group II 150N | Hydrocracking / Catalytic Isodewaxing | $1,105 | $1,150 | $1,135 | +$20/MT | Moderate; reliable Korean spot supply |
| Group II 500N | Hydrocracking / Catalytic Isodewaxing | $1,290 | $1,345 | $1,325 | +$45/MT | Severe Shortage; record $185/MT neutral spread |
| Group III 4 cSt | Severe Hydrocracking / Isomerization | $1,400 | $1,455 | $1,435 | +$25/MT | Firm; high 0W-20/0W-30 engine oil demand |
| Group III 6 cSt / 8 cSt | Severe Hydrocracking / Isomerization | $1,430 | $1,490 | $1,465 | +$30/MT | Constrained; GTL allocation limits in Middle East |
Market dynamics across the three primary categories reveal significant divergence:
- API Group I Resilience: While historical rationalization has permanently shuttered older solvent extraction plants in Europe and Japan, demand for Group I Bright Stock and SN 500 remains exceptionally robust. Bright Stock is indispensable for compounding high-viscosity open gear lubricants, cylinder oils, and ISO VG 320/460 industrial gear oils. With Asian Bright Stock quoted at $1,450/MT FOB, blenders unable to source Group I are forced to substitute expensive polyalphaolefins (PAO) or heavy Group II cuts, driving industrial formulation costs upward.
- API Group II Polarization: As analyzed in Section 5, the market is characterized by acute bifurcated dynamics. While 150N supply remains orderly at $1,105/MT, 500N has surged to $1,290/MT. Several major lubricant blenders in Southeast Asia and South China have been forced to temporarily throttle production runs of ISO VG 68 hydraulic oil due to delayed bulk road-tanker deliveries of 500N.
- API Group III Stability: Premium Group III 4 cSt and 6 cSt base oils maintain an elevated plateau, driven by high global blending mandates for low-viscosity synthetic passenger car motor oils (API SP / ILSAC GF-6 and ACEA C5/C6). Gas-to-Liquids (GTL) plants in the Middle East and catalytic hydrocrackers in South Korea have prioritized captive blending commitments over merchant spot sales.
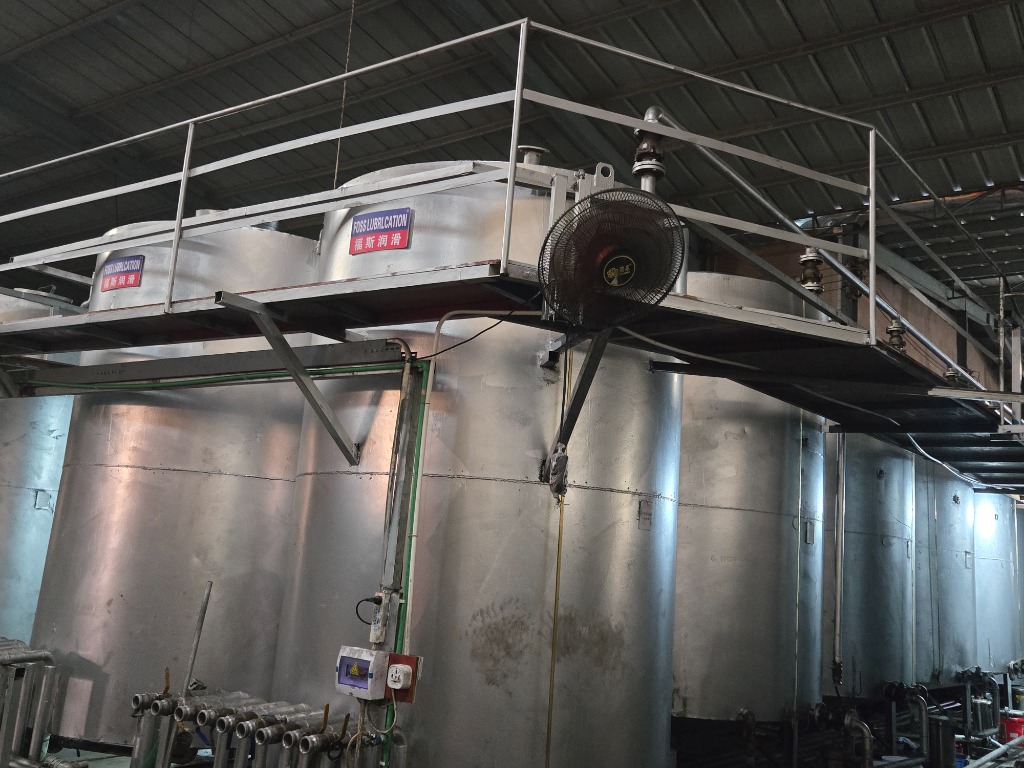
7. Tribological Chemical Additives: ZDDP, Overbased Sulfonates, PMA VI Improvers & Sulfur-Phosphorus EP Precursor Inflation
In addition to base oil feedstock costs, the performance chemical additive package represents between 18% and 32% of total finished lubricant compounding costs. On October 19, 2026, the global additive precursor market reflects persistent cost pressures across critical upstream chemical precursors:
| Additive Chemical Functional Class | Primary Chemical Precursors | Critical Performance Function in Finished Oil | Upstream Cost Trend (Oct 19) | Impact on Finished Formulation Cost |
|---|---|---|---|---|
| Zinc Dialkyldithiophosphate (ZDDP) | Phosphorus Trichloride (PCl3), 2-Ethylhexanol (2-EH), Zinc Oxide (ZnO) | Primary anti-wear, anti-scuffing & primary antioxidant agent in DIN 51524-2 hydraulic oils. | High; 2-EH and yellow phosphorus surged +6.2% | +$1.20 / 208L drum |
| Overbased Calcium Sulfonates (TBN 300/400) | Heavy Alkylbenzene Sulfonic Acid (LABSA), Calcium Hydroxide, CO2 Gas | Acid neutralization, detergency, rust prevention & extreme-pressure film formation. | Firm; alkylbenzene feedstock tight in Asia | +$0.85 / 208L drum |
| Polymethacrylate (PMA) VI Improvers | Methyl Methacrylate (MMA), Long-Chain Fatty Alcohols | Maintains kinematic viscosity at elevated operating temperatures; delivers pour-point depressancy. | Rising; acetone-cyanohydrin route MMA costs up +4.5% | +$1.40 / 208L drum (HV grades) |
| Sulfur-Phosphorus EP Gear Additive Packages | Sulfurized Isobutylene (SIB), Alkyl Acid Phosphates, Amine Salts | Prevents micro-pitting, tooth spalling and scuffing in heavy industrial gearboxes (ISO 12925-1 CKD). | Severe; elemental sulfur and high-purity isobutylene inflation | +$2.20 / 208L drum (CKD 220/320) |
| Phenolic & Aminic Secondary Antioxidants | Di-tert-butylphenol, Diphenylamine (DPA) | Inhibits thermal varnish and sludge generation in high-pressure hydraulic vane and piston pumps. | Stable to firm; European chemical export tariffs | +$0.60 / 208L drum |
8. Packaging Materials & Maritime Freight Economics: Cold-Rolled SPCC Steel Drum Inflation & FOB Xiamen Dispatch
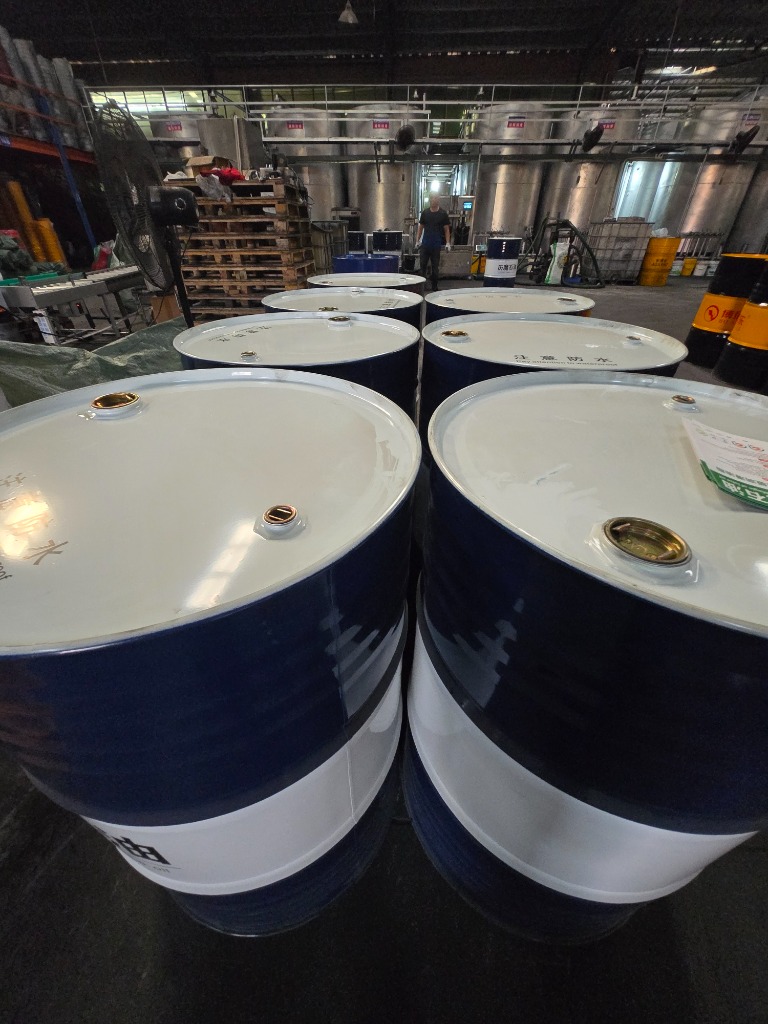
Finished industrial lubricants are packaged and transported under strict physical containment standards. Recent movements in steel packaging materials and maritime container logistics have introduced secondary cost layers that international buyers must account for in their landed cost models:
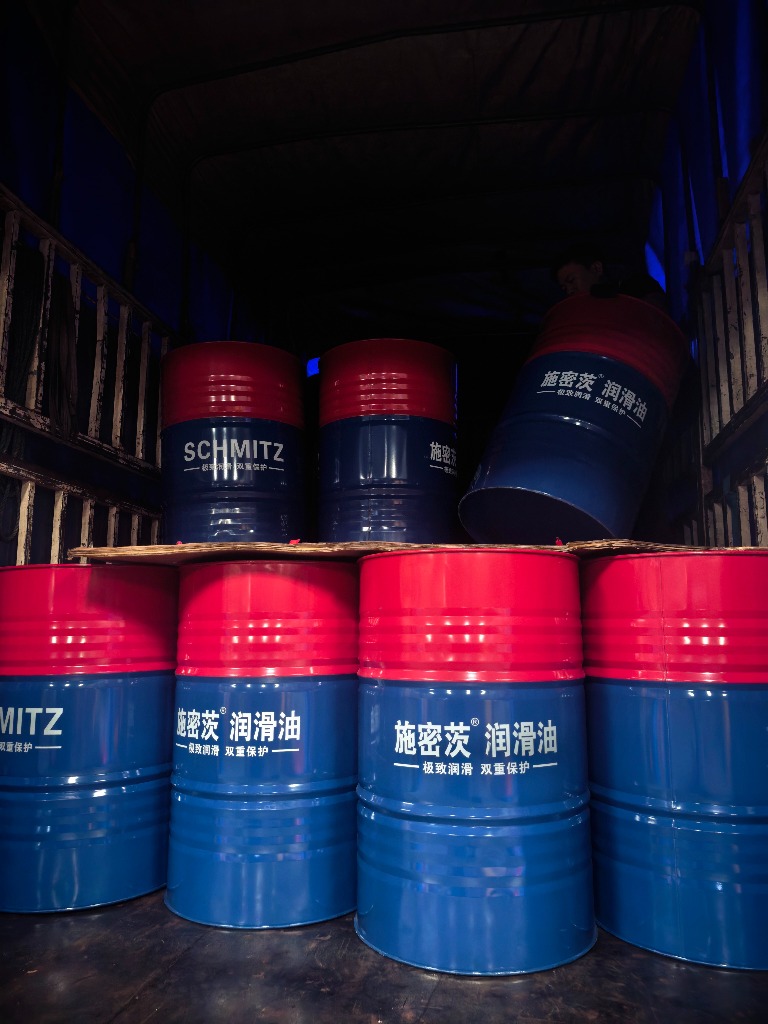
- Cold-Rolled SPCC Steel Drum Costs: The standard industrial packaging medium for global export is the 208-liter (55 US gallon) tight-head steel drum, manufactured from prime cold-rolled SPCC steel sheet with 1.0mm body and 1.2mm head thickness. Rising metallurgical coking coal and hot-rolled coil prices across Asian steel mills (Baosteel, POSCO, Formosa Ha Tinh) have lifted prime export-grade steel drum manufacturing costs to $29.20 per drum. For internal epoxy-phenolic lined drums used for sensitive hydraulic and transformer fluids, prices exceed $33.10 per drum.
- Container Logistics from Xiamen Port: Ocean freight spot rates from Xiamen Port (CNXMN) and Ningbo-Zhoushan to Southeast Asian primary destinations (Singapore, Port Klang, Jakarta, Ho Chi Minh) are quoted at $720–$880 per 20GP container and $1,200–$1,450 per 40HQ container. However, routes to the Middle East (Jebel Ali, Dammam) remain elevated at $2,550 per 40HQ due to vessel diversions and high bunker adjustment factors.
- Weight-Optimized Container Loading: A standard 20-foot dry container accommodates exactly 80 drums of 208L hydraulic oil packed in two tiers of 40 drums each (gross cargo weight ~17.6 MT), well within international road weight limits. Utilizing specialized 40-foot heavy-rated equipment allows 96 to 104 floor-loaded drums, achieving significant per-liter ocean freight economies for large-volume industrial accounts.
9. Authoritative 3-Day Forward Export Price Trajectory Matrix: October 19, 20, and 21, 2026
Integrating upstream crude volatility, physical base oil wholesale pricing, chemical additive indexes, and container logistics surcharges, the FOSS Market Research Desk publishes its daily 3-day predictive export price trajectory for standard export formulations on an FOB Xiamen (CNXMN) basis:
| Product Grade & Specification | Packaging Format | Current FOB Xiamen (Oct 19) | Day 1 Forecast (Oct 20) | Day 2 Forecast (Oct 21) | Day 3 Forecast (Oct 22) | 3-Day Cumulative Outlook |
|---|---|---|---|---|---|---|
| FOSS Anti-Wear Hydraulic Oil ISO VG 32 (L-HM 32) | 208L Steel Drum (Net 175kg) | $199.50 | $201.00 | $202.50 | $203.80 | +$4.30 / drum (+2.2%) |
| FOSS Anti-Wear Hydraulic Oil ISO VG 46 (L-HM 46) | 208L Steel Drum (Net 178kg) | $204.20 | $205.80 | $207.20 | $208.60 | +$4.40 / drum (+2.2%) |
| FOSS Anti-Wear Hydraulic Oil ISO VG 68 (L-HM 68) | 208L Steel Drum (Net 180kg) | $209.00 | $210.60 | $212.00 | $213.50 | +$4.50 / drum (+2.2%) |
| FOSS Heavy-Duty Industrial Gear Oil ISO VG 150 (L-CKD 150) | 208L Steel Drum (Net 182kg) | $231.50 | $233.00 | $234.80 | $236.50 | +$5.00 / drum (+2.2%) |
| FOSS Heavy-Duty Industrial Gear Oil ISO VG 220 (L-CKD 220) | 208L Steel Drum (Net 184kg) | $238.00 | $239.80 | $241.50 | $243.20 | +$5.20 / drum (+2.2%) |
| FOSS Heavy-Duty Industrial Gear Oil ISO VG 320 (L-CKD 320) | 208L Steel Drum (Net 185kg) | $247.50 | $249.50 | $251.50 | $253.50 | +$6.00 / drum (+2.4%) |
| FOSS High Viscosity Index Hydraulic Oil (L-HV 46) | 208L Steel Drum (Net 178kg) | $216.50 | $218.20 | $219.80 | $221.50 | +$5.00 / drum (+2.3%) |
10. Strategic Procurement Hedging Directives: Actionable Recommendations for International Buyers
Given the confluence of rising crude benchmarks, the historic $185/MT Group II 500N spread, additive precursor cost pressures, and container transit lengthening, the FOSS Commercial Strategy Desk issues four mandatory procurement directives for global purchasing directors, mine operators, fleet managers, and industrial plant engineers:
Directive 1: Secure Forward 60-Day Group II 500N and Heavy Gear Oil Formulations Before Asian Refineries Implement November General Price Increases (GPIs)
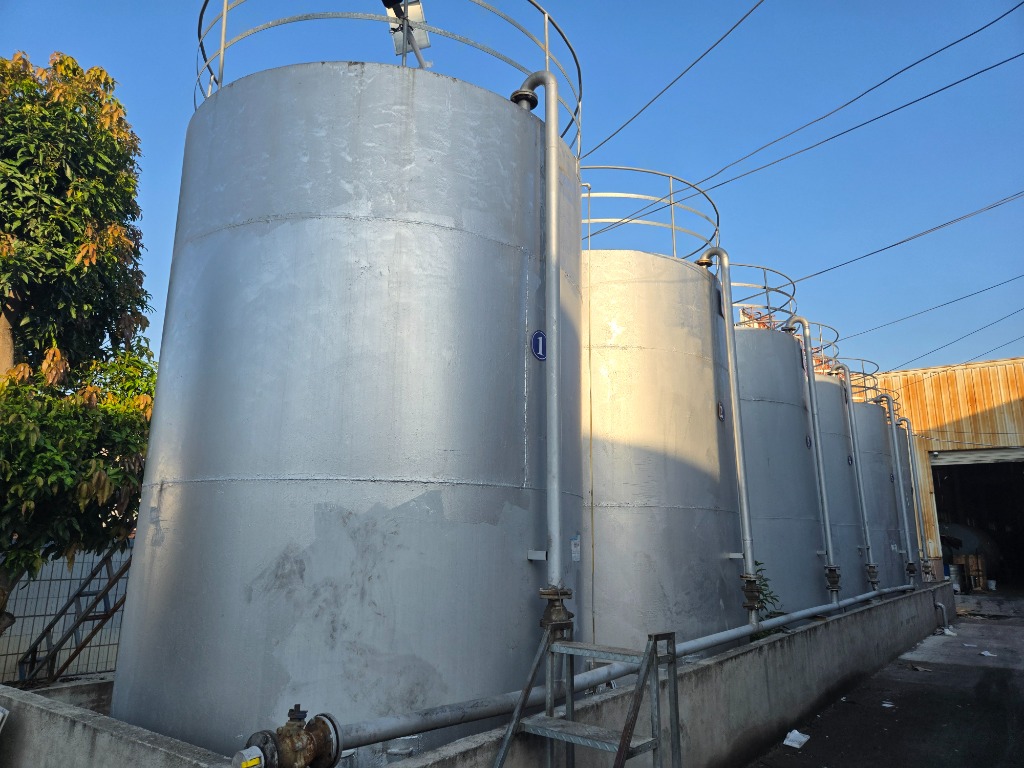
With Group II 500N trading at a record $185/MT premium over 150N and refiners continuing to prioritize middle distillates, major base oil refiners in South Korea and Taiwan are planning November General Price Increases (GPIs) of $45–$65/MT. Commercial buyers requiring ISO VG 46/68 hydraulic oils or ISO VG 150/220/320 gear oils should immediately lock in Q4 quarterly supply agreements with established primary blending facilities that maintain dedicated bulk storage tank farms.
Directive 2: Execute Factory-Direct Fixed-Price Contracts with Primary Blenders to Bypass Broker Markups and Intermediary Margin Stacking
During inflationary commodity cycles, trading intermediaries and offshore brokers compound price volatility by adding speculative trading margins of 8% to 15% on spot container shipments. Direct factory supply agreements with integrated blenders such as FOSS Lubricants allow overseas buyers to contract directly against certified base oil feedstock indexes, ensuring transparent formula pricing, prioritized batch blending slots, and guaranteed maritime container dispatch.
Directive 3: Optimize Container Packing Configurations via Standardized 80-Drum 20GP Two-Tier Palletized or 96-Drum Floor-Loaded Shipments
With container ocean freight and bunker adjustment factors (BAF) elevated due to Cape of Good Hope detours, maximizing cubic and weight utilization per TEU is critical to dampening landed per-liter costs. Transitioning from unoptimized partial loads to standardized 80-drum palletized 20GP configurations (16,640 liters net) or 96-drum floor-loaded shipments reduces per-drum ocean freight costs by $4.50 to $7.20 compared to loose LCL shipping.
Directive 4: Require Batch-Specific Inductively Coupled Plasma (ICP) and Particle Cleanliness (ISO 4406) Certificates of Analysis (COA) to Defend Against Adulterated Low-TBN Spot Blends
In market environments characterized by severe heavy neutral base oil shortages, unscrupulous small-scale toll blenders frequently dilute formulations using low-viscosity spindle oils, off-spec solvent neutral cuts, or substandard non-hydrotreated recycled oils. This compromises thermal-oxidative stability, accelerates hydraulic pump cavitation, and induces rapid sludge formation. Buyers must mandate that every container dispatch be accompanied by a factory-certified Certificate of Analysis (COA) verifying elemental zinc/phosphorus ppm, kinematic viscosity @ 40°C, dielectric demulsibility (ASTM D1401), and ISO 4406 particle cleanliness codes.
11. Technical Engineering Specifications & Quality Verification Standards
FOSS Lubricants manufactures all industrial fluid grades using exclusively hydrotreated Group II and synthetic Group III base stocks compounded with premium additive chemistry sourced directly from global Tier-1 manufacturers (including Lubrizol, Afton Chemical, Infineum, and Chevron Oronite). Our finished fluids fully satisfy and exceed global OEM and international tribological standards:
| Physical & Chemical Parameter | Test Method (ASTM / ISO) | FOSS L-HM 32 | FOSS L-HM 46 | FOSS L-HM 68 | FOSS L-CKD 220 Gear Oil |
|---|---|---|---|---|---|
| Kinematic Viscosity @ 40°C (mm²/s) | ASTM D445 / ISO 3104 | 31.5 – 33.5 | 43.8 – 47.2 | 64.5 – 69.5 | 210.0 – 230.0 |
| Kinematic Viscosity @ 100°C (mm²/s) | ASTM D445 / ISO 3104 | 5.4 | 6.8 | 8.7 | 19.2 |
| Viscosity Index (VI) | ASTM D2270 / ISO 2909 | ≥ 102 | ≥ 104 | ≥ 102 | ≥ 98 |
| Density @ 15°C (kg/m³) | ASTM D4052 / ISO 12185 | 862 | 868 | 874 | 892 |
| Flash Point COC (°C) | ASTM D92 / ISO 2592 | ≥ 220 | ≥ 230 | ≥ 240 | ≥ 245 |
| Pour Point (°C) | ASTM D97 / ISO 3016 | ≤ -28 | ≤ -26 | ≤ -24 | ≤ -18 |
| Copper Strip Corrosion (3h @ 100°C) | ASTM D130 / ISO 2160 | Class 1a | Class 1a | Class 1a | Class 1b |
| Air Release @ 50°C (minutes) | ASTM D3427 / ISO 9120 | ≤ 4.0 | ≤ 5.5 | ≤ 7.0 | ≤ 10.0 |
| Demulsibility @ 54°C (40-40-0, minutes) | ASTM D1401 / ISO 6614 | ≤ 12 | ≤ 15 | ≤ 18 | ≤ 25 (@ 82°C) |
| FZG Gear Test (Failure Load Stage) | DIN 51354-2 / ISO 14635-1 | Stage ≥ 11 | Stage ≥ 12 | Stage ≥ 12 | Stage ≥ 14 |
| Particle Cleanliness Code | ISO 4406 / NAS 1638 | 16/14/11 (NAS 5) | 16/14/11 (NAS 5) | 16/14/11 (NAS 5) | 18/16/13 (NAS 7) |
12. Conclusion & Factory Contact for Direct Spot & Term Orders
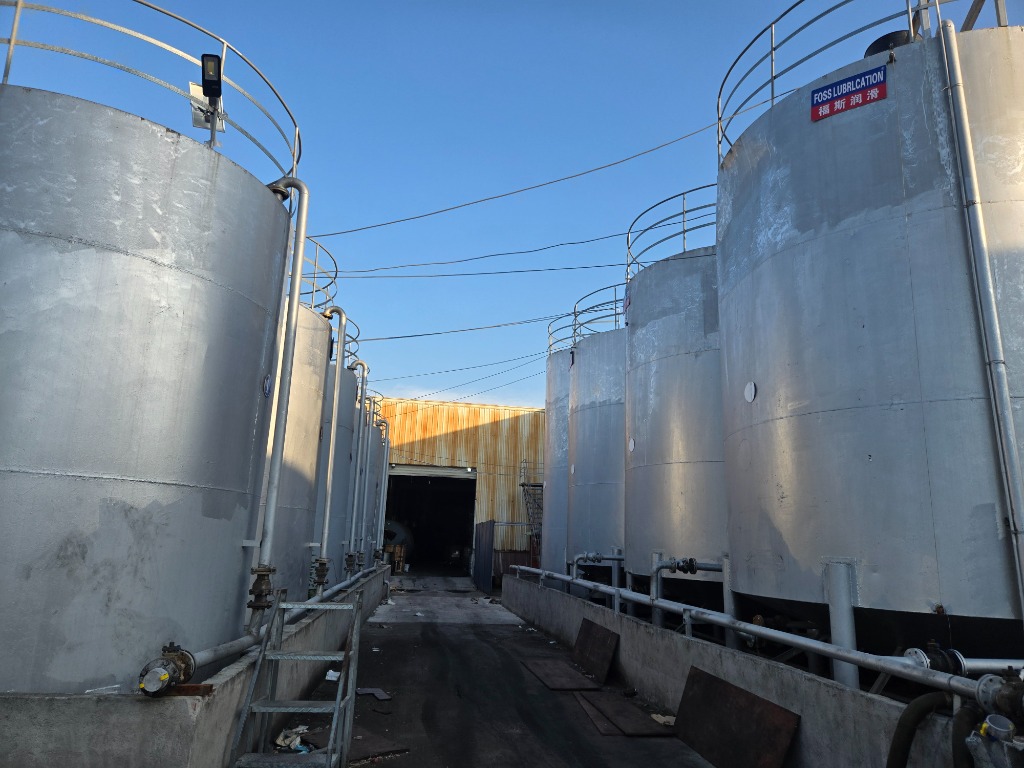
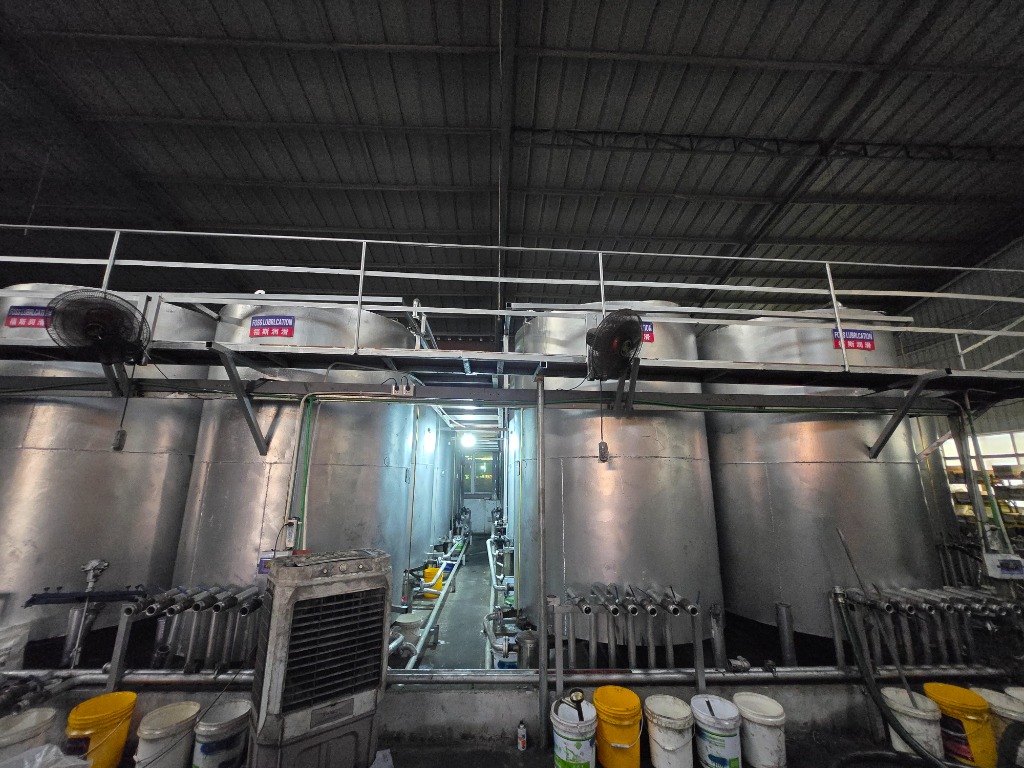
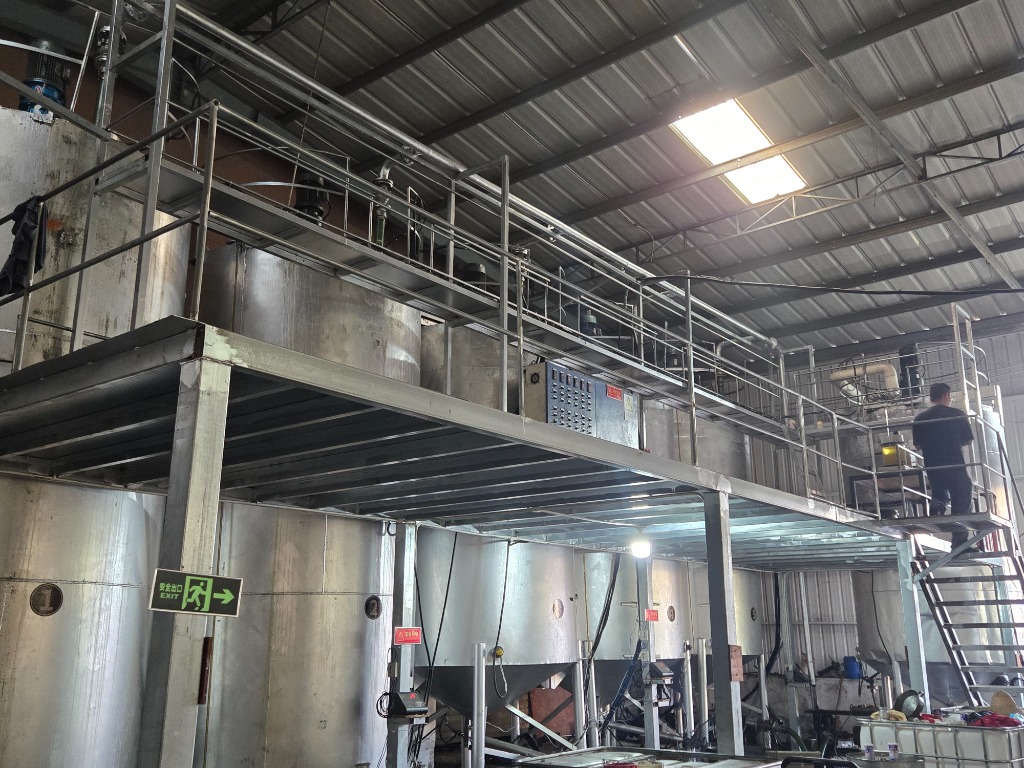
As the global energy complex navigates sustained crude strength, refinery middle-distillate conversion competition, and naval transit friction, FOSS Lubricants provides international buyers with an anchored, transparent, and direct manufacturing partnership. Our 35,000 MT bulk storage infrastructure, automated DCS blending reactors, and seamless export container handling at Xiamen Port insulate overseas partners from spot market rationing and broker markups.
To secure your Q4 allocation, request batch Certificates of Analysis (COA), or obtain fixed-price FOB/CIF quotations for 20GP or 40HQ container shipments, please contact our international commercial dispatch team:
FOSS Lubrication International Commercial Desk
Factory Address: Quanzhou High-Tech Industrial Zone, Quanzhou, Fujian 362000, China
Export Port: Port of Xiamen (CNXMN) / Port of Quanzhou (CNQZ)
WhatsApp / Direct Inquiry Line: +86 159 5954 3210
Telegram Global Desk: @foss_lubricants_cis
Official Web Portal: www.fosslubricants.com
Definitive 3-Day Lubricant & Base Oil Trend Forecast
Synthesized by the FOSS Quantitative Energy Modeling Desk based on active shipping line container bookings, regional tank farm draw-down rates, and prompt ICE Brent futures sentiment:
Brent crude futures establish firm support between $88.40 and $89.20/bbl; Northeast Asian merchant refiners push Group II 500N spot offers toward $1,290–$1,295/MT as Singapore middle-distillate crack spreads consolidate above $24.20/bbl.
Extended Cape of Good Hope transits absorb container and parcel tanker tonnage; higher bunker surcharges and Lloyd's AWRP lift export quotations for DIN 51524-2 hydraulic oils toward $205.80/drum FOB.
Compounding cost pressures from the historic $185/MT 500N neutral premium and tight Group I Bright Stock allocation force international distributors to finalize 40HQ container bookings to secure guaranteed factory dispatch slots.
5. Strategic Sourcing & Hedging Directives for Overseas Importers
For overseas procurement directors, fleet operators, and industrial distributors, market volatility represents both operational risk and competitive opportunity. We recommend the following three concrete actions for managing Q4 procurement:
Lock 60-Day Container Requirements
Secure firm proforma invoices (PI) with 30-day price validity. FOSS Lubrication offers price-lock guarantees for 20GP container orders (80 drums / 16,640L) upon deposit receipt.
Audit Laboratory CoA Verification
Demand full pre-shipment ASTM test parameters: kinematic viscosity at 40°C / 100°C, viscosity index ≥ 100, flash point ≥ 220°C, pour point ≤ -15°C, and zero moisture contamination.
FOSS Lubrication: Factory-Direct Precision Engineering
Operating out of Quanzhou, China, FOSS blends over 20,000 MT annually of ISO VG 32/46/68 anti-wear hydraulic oils, CK-4 heavy-duty engine oils, and industrial gear lubricants. Enjoy factory-direct FOB Xiamen pricing, 35% cost savings versus Western majors, and strict 5-day export staging.