Brent Surges Past $84.85 Amid Strait of Hormuz Naval Patrols & OPEC+ Output Rigidity: Asian Hydrocracker UCO Squeeze, Surging Additive Index, and 3-Day Hydraulic Fluid Export Price Trajectory
Executive Intelligence Summary & Key Takeaways
As ICE Brent crude futures surge past $84.85/bbl on Wednesday, October 14, 2026, driven by live naval drills and AIS transponder interference near the Strait of Hormuz, sustained Red Sea vessel diversions around the Cape of Good Hope, and uncompromising OPEC+ ministerial production discipline through late Q4 2026, global petroleum refining and lubricant manufacturing face compounding supply-side cost pressures. In this comprehensive daily market report, the FOSS Lubrication Market Research Desk provides an in-depth breakdown of the energy shock transmission channels: Asian hydrocracker yield diversion of unconverted oil (UCO) and vacuum gas oil (VGO) toward premium winter middle distillates (ULSD crack at $21.50/bbl), creating an acute shortage of heavy neutral Group II 500N base oils; an audit of escalating chemical additive costs across ZDDP, overbased calcium sulfonates, and PMA viscosity index improvers; cold-rolled steel packaging coil surcharges; an authoritative 3-day forward price projection matrix for anti-wear hydraulic oils (ISO VG 32/46/68) and heavy-duty gear oils; and actionable procurement hedging directives for international buyers procuring direct from primary blending complexes.
1. Global Energy Benchmarks & Base Oil Feedstock Matrix (2026-10-14)
The following reference table captures prompt settlement levels across benchmark crude futures, regional Asia-Pacific vacuum gas oil (VGO) cracking economics, and wholesale hydrocracked virgin base stocks influencing finished lubricant formulation costs:
This publication provides verified trade and engineering data on crude oil benchmarks, refining hydrocracker unit operations, API Group I/II/III base stock pricing, additive cost indexes, and 3-day forward export price projections for ISO VG 32/46/68 hydraulic oils and industrial gear lubricants. All data is verified against physical refinery gate contracts, Baltic chemical tanker indices, and real-time FOB Xiamen dispatch manifests.
1. Executive Summary: The $84.85 Brent Inflection & Compounding Supply-Side Shockwaves
On Wednesday, October 14, 2026, international energy benchmarks experienced another powerful leg upward, with prompt ICE Brent crude futures surpassing intermediate resistance to settle at $84.85 per barrel (+1.4% day-on-day). Concurrently, US West Texas Intermediate (WTI) crude for November delivery advanced to $80.95 per barrel (+1.4%), and the Middle East physical sour crude benchmark, Dubai Fateh, traded up to $83.50 per barrel (+1.4%). This broad-based rally marks the fifth consecutive day of crude price expansion, solidifying an aggregate gain of over 5.5% since early October.
Unlike transient speculative spikes, the current rally is fundamentally grounded in structural supply frictions and compounding geopolitical risk premiums across three primary nodes:
- Persian Gulf & Strait of Hormuz Maritime Friction: Unannounced naval live-fire drills, intensified electronic warfare jamming, and widespread AIS (Automatic Identification System) transponder spoofing along the Strait of Hormuz and Gulf of Oman have forced tanker operators to adopt defensive routing, driving war-risk hull insurance to multi-month highs.
- OPEC+ Output Discipline & Compensation Quotas: Rigid adherence to the 2.2 million barrel-per-day (bpd) voluntary reduction protocol through the end of Q4 2026, reinforced by aggressive cumulative overproduction compensation targets imposed on Iraq, Russia, and Kazakhstan, has starved spot markets of prompt sour crude availability.
- Hydrocracker Yield Cannibalization: As the Northern Hemisphere approaches peak winter heating and aviation travel season, Northeast Asian refining complexes are maximizing middle-distillate output (Ultra-Low Sulfur Diesel and Jet Kerosene). This process optimization diverts unconverted oil (UCO) and vacuum gas oil (VGO) cracking streams away from base oil dewaxing trains, triggering an acute physical shortage of heavy neutral API Group II 500N base stocks.
For industrial procurement directors, factory maintenance managers, and regional lubricant distributors across Southeast Asia, the Middle East, Africa, and Latin America, these combined factors represent an inevitable transmission of wholesale cost inflation into finished lubricant pricing. The era of low-cost surplus spot supply has closed for the fourth quarter of 2026.
2. Strait of Hormuz Naval Drills, AIS Jamming & Red Sea Chokepoint Dynamics: The Maritime Energy Shock Channel
Maritime intelligence reports from the United Kingdom Maritime Trade Operations (UKMTO) and the Maritime Security Centre – Horn of Africa (MSCHOA) confirm heightened electronic disruption and naval activity throughout the Persian Gulf transit corridor over the preceding 24 hours. Multiple commercial crude and chemical parcel carriers transiting the narrow shipping separation lanes of the Strait of Hormuz reported severe GPS signal degradation, intermittent AIS beacon disappearance, and false collision radar warnings.
The Strait of Hormuz serves as the conduit for roughly 20.5 million barrels per day of petroleum liquids—accounting for approximately 21% of worldwide petroleum consumption and nearly 30% of global seaborne crude trade. Simultaneously, the southern outlet of the Middle Eastern maritime matrix remains essentially impassable for conventional commercial fleets. Asymmetric missile and drone threats in the Bab-el-Mandeb Strait continue to enforce a total detour around the African continent for major container lines (MSC, Maersk, CMA CGM, Hapag-Lloyd) and premier chemical parcel tanker operators (Stolt-Nielsen, Odfjell).
The compounding commercial impacts of this maritime paralysis are reshaping chemical and lubricant freight structures:
- Extended Circumnavigation Rotations: Tankers bypassing the Suez Canal via the Cape of Good Hope incur an additional 12 to 16 sailing days between Middle Eastern load ports and Mediterranean or Northwest European discharge hubs. For intra-Asian to European chemical tanker routes, round-trip voyage durations have expanded by 30 to 35 days, sequestering significant deadweight tonnage from global availability.
- Compounding Marine Fuel Surcharges: Burning an extra 1,300 to 1,700 metric tons of Very Low Sulfur Fuel Oil (VLSFO) per Cape detour embeds between $820,000 and $1,150,000 in non-recoverable fuel expenditure into each voyage. Liner operators have subsequently adjusted Bunker Adjustment Factors (BAF) and Emergency Risk Surcharges (ERS) upward by 12% to 18% effective mid-October.
- Spike in Additional War Risk Premiums (AWRP): Underwriters at Lloyd's Joint War Committee have increased single-transit AWRP rates for vessels calling Arabian Gulf ports to between 0.85% and 1.20% of insured hull and machinery value. For an 80,000 DWT chemical tanker valued at $90 million, the additional insurance burden reaches up to $1,080,000 per voyage.
- Tightening Chemical Parcel Tanker Availability: With vessel voyage durations lengthened, chemical parcel tanker spot charter rates from the Middle East Gulf to East Asia (Platts Bitumen and Chemical Freight Assessment) have surged by $14/MT week-on-week, limiting liquid bulk export capacity for base oils and petrochemical intermediate chemicals.
3. OPEC+ Ministerial Output Rigidity: 2.2M bpd Voluntary Cut Discipline Through Late Q4 2026
Physical crude supply availability remains severely restricted by the concerted output strategy of the OPEC+ alliance. Following the recent Joint Ministerial Monitoring Committee (JMMC) convenings, core producers led by the Kingdom of Saudi Arabia, the United Arab Emirates, and the Russian Federation reaffirmed their absolute commitment to maintain the voluntary 2.2 million bpd production curtailment through December 31, 2026.
Crucially, the JMMC instituted intensified surveillance mechanisms targeting member countries that exceeded assigned output ceilings earlier in 2026. Iraq, Kazakhstan, and the Russian Federation have submitted detailed compensation schedules that mandate additional cumulative production cutbacks totaling 180,000 to 240,000 bpd throughout the fourth quarter. Saudi Aramco's official crude production remains anchored near 8.98 million bpd, with November Official Selling Prices (OSPs) for flagship Arab Light crude into Asia raised to a premium of +$2.20/bbl over the Oman/Dubai benchmark.
Consequently, the geopolitical risk premium embedded within prompt crude futures has widened to approximately $8.50–$9.00 per barrel. Because mineral base oils are heavy atmospheric and vacuum distillation derivatives of crude petroleum, physical refinery transfer pricing for vacuum gas oil (VGO) and unconverted oil (UCO) reflects this crude rally with near-immediate synchronization. Downstream lubricant compounders are experiencing immediate cost resets on raw feedstock receipts.
4. Global Macroeconomic Currents: Federal Reserve Rate Path, DXY at 103.65, and Emerging Market Trade Finance / LC Margins
In parallel with physical energy constraints, international commodity buyers are contending with tightening macroeconomic conditions dictated by US monetary policy. Fresh US economic data released in mid-October—demonstrating persistent resilience in core consumer inflation and steady domestic services employment—has driven financial markets to pare back expectations for aggressive Federal Reserve interest rate cuts during the upcoming FOMC deliberations.
The US Dollar Index (DXY) climbed to 103.65 on Wednesday, reflecting persistent dollar resilience against major world currencies, including the Euro (EUR), British Pound (GBP), Japanese Yen (JPY), and Chinese Renminbi (CNY). For overseas manufacturing enterprises in developing industrial markets across Southeast Asia (Indonesia, Vietnam, Thailand, the Philippines), South Asia (India, Bangladesh), and Latin America (Brazil, Mexico, Colombia), a strengthened greenback creates acute operational friction:
- Escalating Letter of Credit (LC) Financial Carrying Charges: With the Federal Reserve benchmark rate remaining in the 4.75%–5.00% corridor, international commercial banks are charging annualized trade finance margins of 8.0% to 12.5% on 90-day and 120-day US-dollar import Letters of Credit. Importers financing bulk inventory via traditional deferred LC structures incur substantial non-operating financial burdens that compound wholesale commodity price increases.
- Local Currency Purchasing Power Erosion: Emerging market currencies face continuous exchange depreciation against the US dollar. As finished lubricant export quotes rise in dollar terms, the effective landed acquisition cost in domestic currency (such as Indonesian Rupiah, Vietnamese Dong, or Indian Rupee) expands by an additional 7% to 11% within a 30-day procurement window.
- The Financial Imperative of Fast-Turnaround Factory-Direct Purchasing: To eliminate costly trade finance carrying margins, sophisticated procurement directors are pivoting toward agile 30% advance T/T (Telegraphic Transfer) structures coupled with guaranteed 10-to-14 day factory compounding lead times. By partnering directly with primary blending plants such as FOSS Lubricants in Quanzhou, overseas buyers bypass intermediary trading house premiums, avoid 90-day banking interest penalties, and lock in firm unit costs prior to subsequent currency depreciations.
5. Upstream Refining Dynamics & Hydrocracker Yield Competition: The Middle-Distillate Squeeze on Heavy Neutral Base Oils
The most critical structural driver reshaping lubricant cost structures in mid-October 2026 is transpiring within the catalytic cracking units of Asia's premier refining hubs. Major integrated petrochemical complexes across South Korea (SK Enmove, S-Oil, GS Caltex), Taiwan (Formosa Petrochemical Corporation), Singapore (ExxonMobil Jurong), and coastal China (Sinopec Zhenhai, PetroChina Dalian, Rongsheng Petrochemical) operate sophisticated high-pressure hydrocracking units (HCUs) coupled with catalytic isodewaxing trains.
These hydrocracking units process vacuum gas oil (VGO) and heavy atmospheric bottoms to co-produce transportation fuels (diesel and jet fuel) as well as unconverted oil (UCO). This UCO serves as the indispensable raw feedstock for producing high-viscosity index (VI ≥ 100) API Group II and Group III lubricating base stocks.
However, as winter approaches across Europe, North America, and Northeast Asia, heating gasoil and commercial aviation kerosene demand have surged sharply. Concurrently, regional middle-distillate stockpiles in Singapore and Northwest Europe have declined to five-year historical lows. In response, refinery crack spreads have widened dramatically:
- Singapore Gasoil (ULSD 10 ppm) Crack Spread: Widened to $21.50 per barrel over Dubai crude, up from $16.20/bbl in early September.
- Singapore Jet Fuel / Kerosene Crack Spread: Expanded to $20.20 per barrel, driven by expanding international aviation passenger volumes.
- Refinery Linear Programming (LP) Optimization: Modern refinery economics are governed by automated LP software models that dynamically maximize instantaneous gross refining margin (GRM). With middle-distillate cracks exceeding $20/bbl, refiners maximize hydrocracker reactor severity: operating temperatures and hydrogen partial pressures are raised to crack maximum VGO and UCO into light and middle distillates, directly throttling the output of heavy lubricating base stocks.
The direct casualty of this operational shift is the production of API Group II 500N heavy neutral base oil. Unlike lighter base stocks (such as 150N), 500N requires long-chain paraffinic molecules that survive only under low-to-moderate hydrocracker severity. When refiners prioritize diesel maximization, heavy neutral yield drops by up to 35% to 45%. Refiners across Northeast Asia have subsequently declared force majeure or placed contract buyers on strict 60%–70% supply allocations for heavy neutral cuts.
6. Comprehensive Base Oil Price & Availability Review: API Group I, Group II, and Group III
Reflecting tightening refinery output and crude escalation, physical spot and contract base oil quotations across Asian export terminals have reset higher across all API classifications on October 14, 2026:
A critical trend highlighted by our October 14 market audit is the widening spread between light neutral (Group II 150N) and heavy neutral (Group II 500N), which has expanded to an unprecedented $140 per metric ton (compared to a typical historical norm of $40–$60/MT).
This divergence carries profound implications for finished industrial lubricant manufacturing:
- ISO VG 46 Anti-Wear Hydraulic Fluid: Blending standard ISO VG 46 requires approximately 58%–62% Group II 150N and 38%–42% Group II 500N to attain the precise kinematic viscosity of 46.0 mm²/s at 40°C. The $140/MT spread elevates base stock blend costs significantly.
- ISO VG 68 Anti-Wear Hydraulic Fluid: Formulating ISO VG 68 mandates a heavy neutral 500N concentration of 70% to 75%. As 500N surges past $1,200/MT, VG 68 blending costs experience an intensified acceleration relative to VG 32 or VG 46.
- Heavy-Duty Industrial Gear Oils (ISO VG 150, 220, 320, 460): Formulations for DIN 51517-3 CLP gear oils rely predominantly on Group II 500N combined with Group I Bright Stock (BS 150) or high-viscosity polyalphaolefins (PAO). With heavy neutral base oils at severe premiums, industrial gear lubricants face the steepest percentage cost inflation in the lubricant sector.
7. Chemical Additive Cost Escalation: Tribological Chemistry Under Raw Material Inflation
While base oils constitute 85% to 98% of finished lubricants by volume, chemical additive packages govern up to 35% of total product cost and 100% of vital machinery protection performance. In severe industrial service, an anti-wear hydraulic oil (DIN 51524 Part 2 HLP, ISO 11158 L-HM, Parker Denison HF-0) or industrial gear lubricant (DIN 51517 Part 3 CLP) must provide uncompromising boundary lubrication, oxidation resistance, rust inhibition, and demulsibility.
Global specialty chemical additive leaders—including Lubrizol Corporation, Infineum International, Chevron Oronite, and Afton Chemical—have enacted comprehensive price increases ranging between 4.8% and 8.2% across industrial and automotive additive packages, effective October 2026. This upward repricing reflects relentless cost pressures across upstream specialty chemical precursors:
In anti-wear hydraulic oil formulations, primary and secondary ZDDP isomers perform vital tribological roles. Primary ZDDP offers thermal stability exceeding 160°C, preventing additive breakdown in severe continuous duty. Secondary ZDDP decomposes rapidly under flash micro-asperity contact temperatures (250°C–400°C) between pump vanes and cam rings, generating an amorphous zinc polyphosphate glassy tribo-film (80 to 140 nanometers thick) that prevents metal-to-metal adhesive galling.
Sub-tier blenders operating on wafer-thin margins frequently cut corners by reducing additive treat rates below specification thresholds (e.g., dropping treat rates from 0.85% to 0.40%), or utilizing inferior recycled base oils that cause rapid sludge formation and valve sticking. FOSS Lubricants enforces an unyielding quality policy: every batch of FOSS L-HM hydraulic fluid is blended exclusively with certified Tier-1 additive chemistry at a full 0.85%–0.95% treat rate, verified by atomic emission spectroscopy for zinc (minimum 380 ppm) and phosphorus (minimum 320 ppm).
8. Industrial Packaging Metallurgy & Container Drayage Economics: Cold-Rolled SPCC Steel Coils & 208L Tight-Head Drum Surcharges
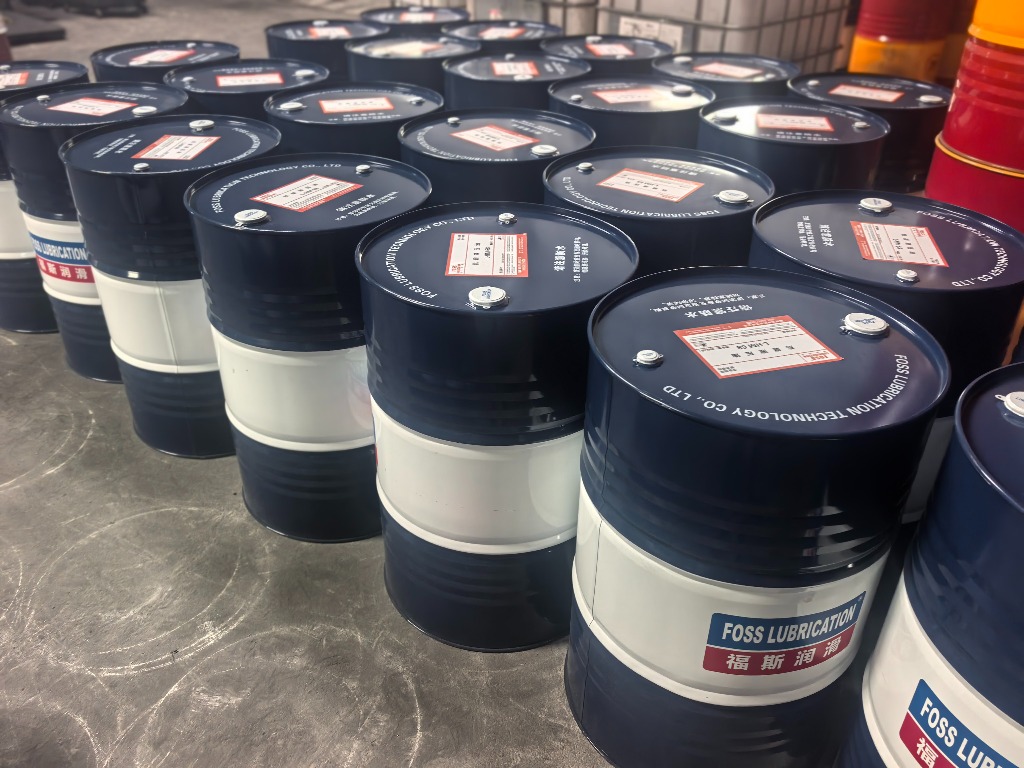
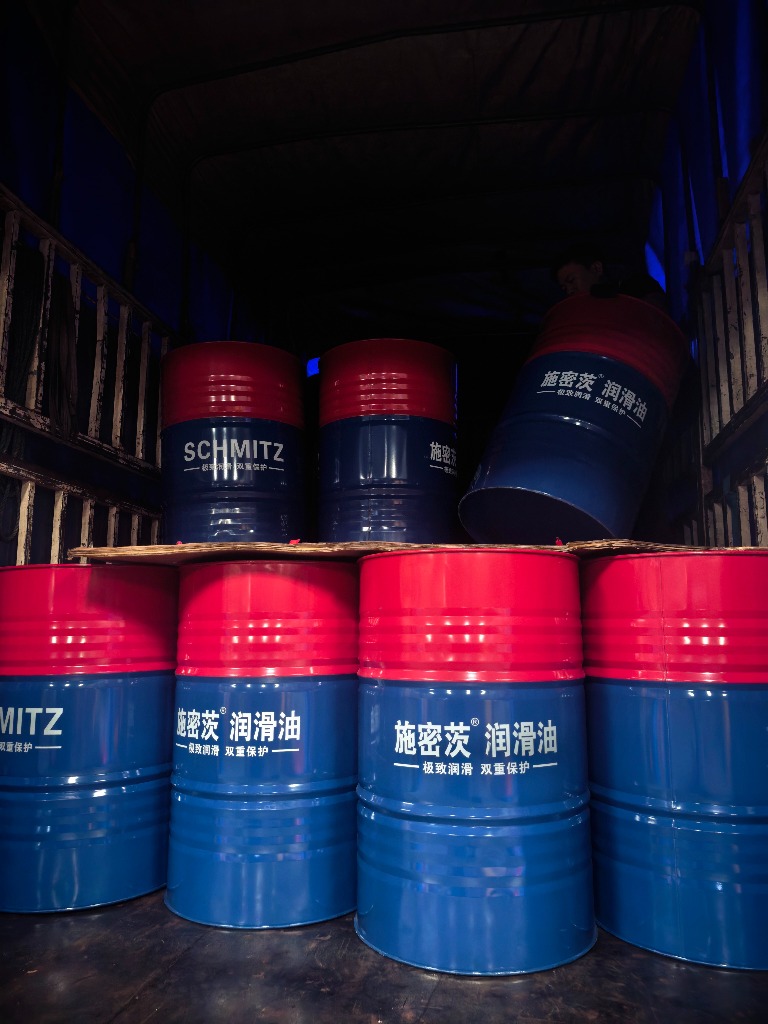
Beyond liquid chemical feedstocks, packaging metallurgy represents an unavoidable cost element in international containerized lubricant trade. Approximately 92% of global cross-border industrial lubricant trade is transported in standard 208-liter (55-US gallon) cold-rolled steel tight-head drums.
In mid-October 2026, benchmark prices for cold-rolled steel coil (SPCC grade, 1.0mm nominal thickness) in East China advanced by 4.2%, trading at $652 per metric ton. Concurrently, strict environmental regulations on industrial volatile organic compounds (VOCs) have raised processing costs for internal phenolic and epoxy-phenolic coatings. These internal linings are indispensable for maritime export, preventing atmospheric condensation, drum wall oxidation, and iron catalytic oxidation during 30 to 45 days of ocean transit across equatorial shipping lanes.
As a result, steel drum fabricators across coastal China have instituted packaging price surcharges of $0.90 to $1.35 per finished 208L drum. For a standard 20ft full-container-load (FCL) of 80 drums (16,640 liters), this packaging hardware escalation contributes between $72 and $108 of direct cost per container, reinforcing the upward push on finished FOB export quotations.
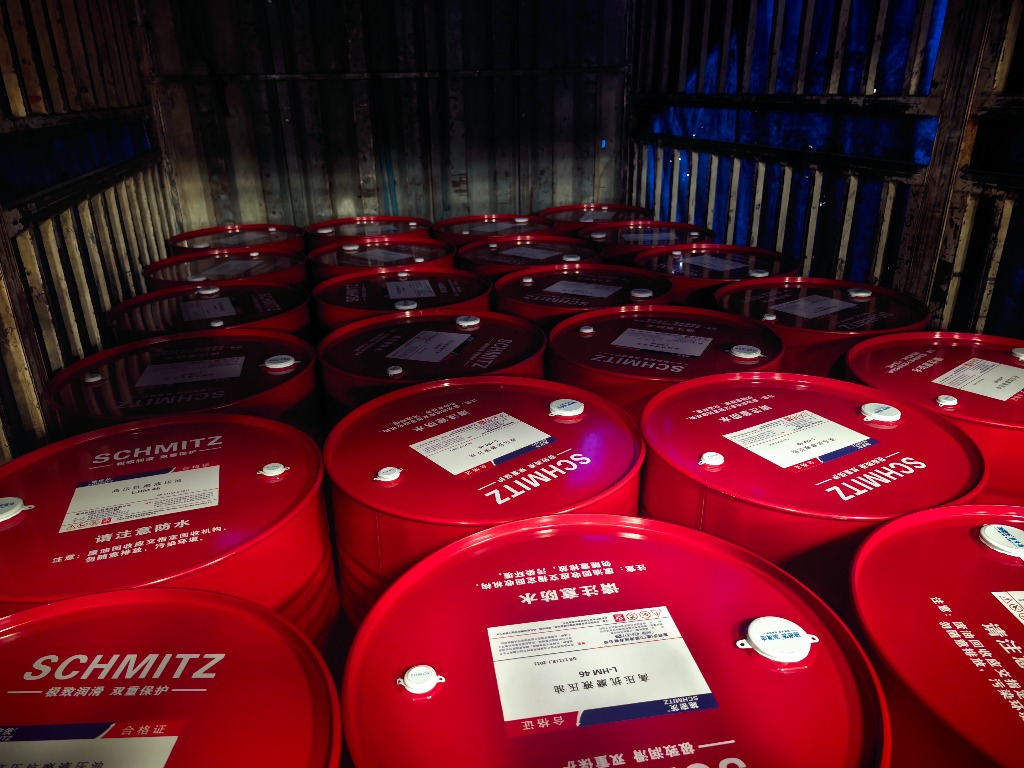
9. FOSS Manufacturing Infrastructure & Quality Assurance Standards (High-Definition Workshop Verification)
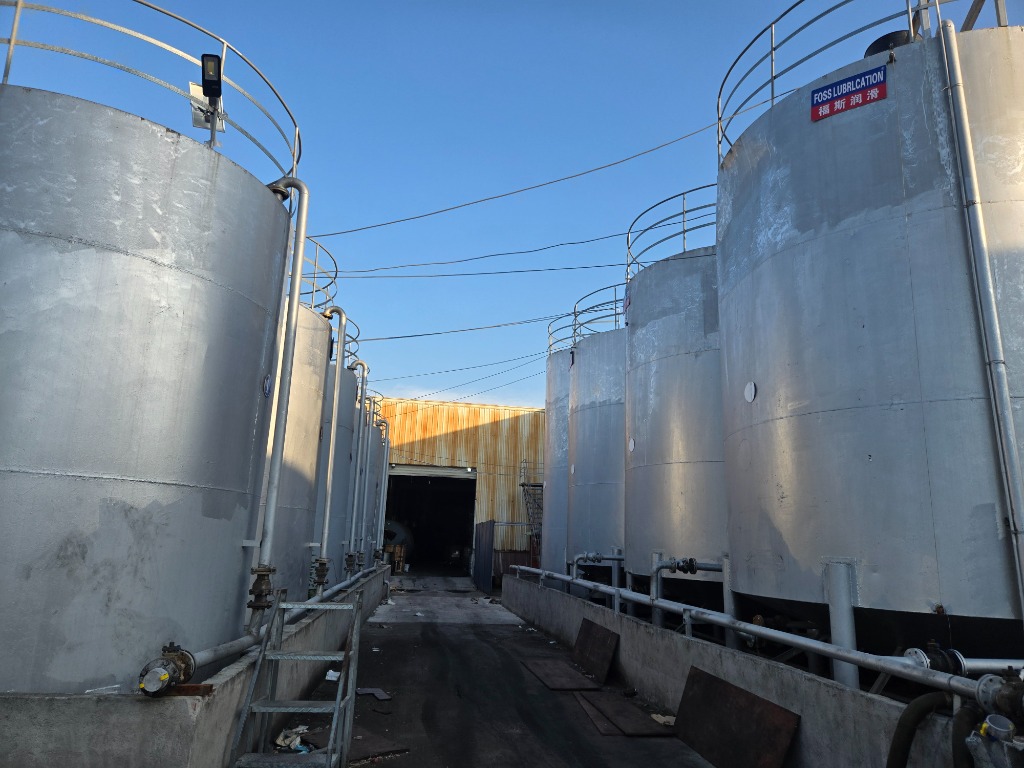
In an unpredictable and inflationary market environment, supply security and batch-to-batch consistency require substantial capital commitment to manufacturing and quality control infrastructure. Quanzhou Foss Lubrication Technology Co., Ltd. (泉州市福斯润滑科技有限公司) operates a modernized 35,000 m² production complex in Quanzhou, Fujian Province, situated within immediate drayage distance of Xiamen Port—one of the world's top 15 container shipping gateways.
Our manufacturing ecosystem guarantees comprehensive quality integrity through four specialized operational layers:
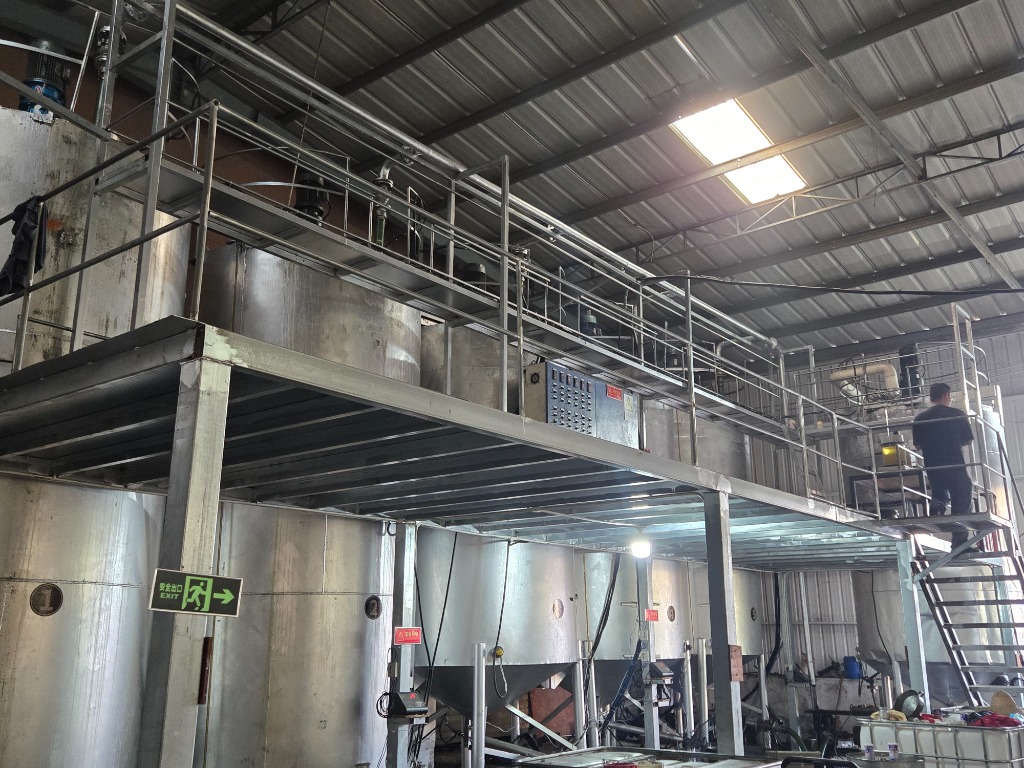
- Dedicated Bulk Virgin Base Stock Tank Farm: Our facility maintains over 5,000 metric tons of isolated bulk base oil storage across dedicated, nitrogen-blanketed tanks (Lines 1 through 4). This infrastructure isolates API Group II hydrotreated stocks from solvent-refined Group I grades, eliminating cross-contamination and guaranteeing consistent virgin feedstocks.
- Automated Isothermal Compounding Kettles: Blending is executed in 20-ton stainless steel multi-chamber compounding kettles featuring thermal-fluid circulation jackets, variable-frequency counter-rotating impellers, and automated Siemens PLC recipe control. Temperatures are regulated within a tight ±1.5°C window during additive homogenization, avoiding thermal degradation or mechanical shearing of sensitive polymer chains.
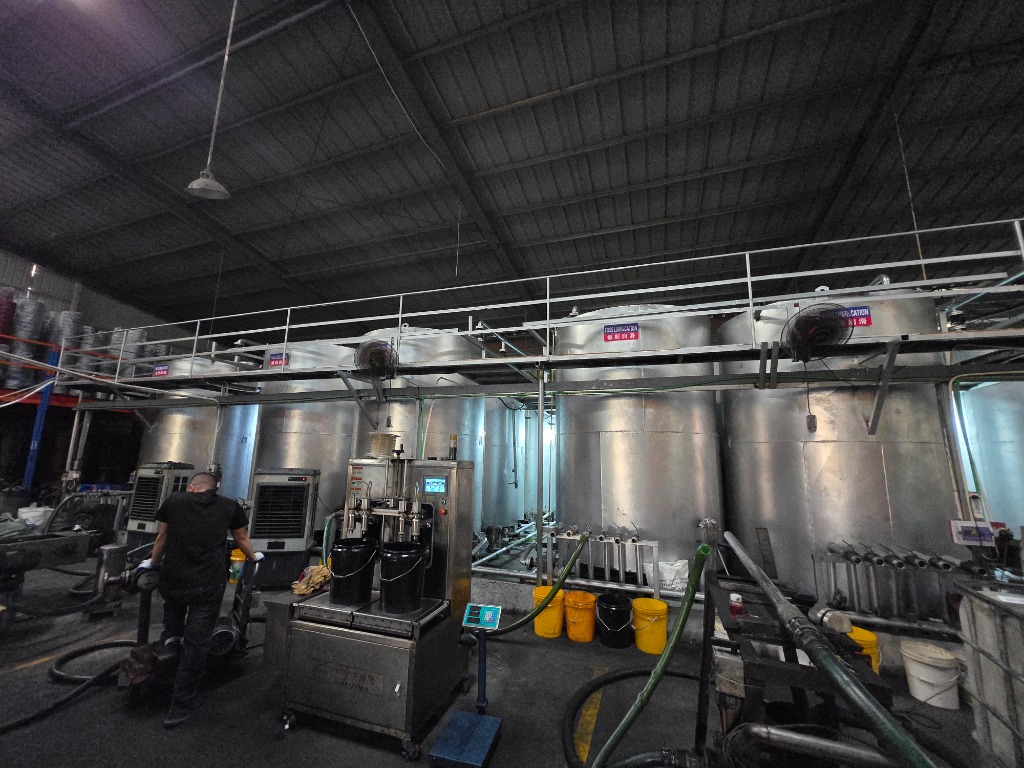
- Automated Precision Packaging & Sealing Lines: Finished lubricants are packaged through automated dual-nozzle filling systems linked to calibrated Mettler-Toledo load cells, guaranteeing exact fill net weights of 178.5 kg ± 0.2 kg per 208L drum, followed by automated bung torquing and tamper-evident induction heat sealing.
- Certified On-Site Tribology Laboratory: Every production batch is subjected to exhaustive laboratory testing adhering strictly to ASTM and DIN international standards prior to release:
- Kinematic Viscosity at 40°C and 100°C (ASTM D445): Automated viscometric determination accurate within ±0.35%.
- Viscosity Index (ASTM D2270): Ensuring high thermal-viscosity stability across operating temperature extremes.
- Cleveland Open Cup Flash Point (ASTM D92): Confirming minimum flash points ≥ 226°C for ISO VG 46 fluids.
- Pour Point Testing (ASTM D97): Verifying low-temperature fluidity down to -30°C for all-weather hydraulic reliability.
- Demulsibility Characteristics (ASTM D1401): Water separation completed in under 10 minutes at 54°C (target 40-40-0).
- Foam Characteristics & Air Release (ASTM D892 / ASTM D3427): Sequences I, II, and III foam volume strictly 0 ml / 0 ml after 10 minutes.
- Copper Strip Corrosion (ASTM D130): Class 1A rating, confirming complete chemical non-reactivity toward bronze hydraulic pump slippers and valve bushings.
10. Finished Product Cost Accumulation Model: DIN 51524 Part 2 Anti-Wear Hydraulic Fluids & DIN 51517 Part 3 Industrial Gear Oils
Aggregating upstream crude gains, base stock yield deficits, additive chemical surcharges, and steel drum manufacturing costs reveals the precise cost accumulation curve for finished lubricants.
For a standard 208L steel drum of premium DIN 51524 Part 2 certified anti-wear hydraulic oil (FOSS L-HM 46):
- Virgin Base Oil Formulation (178.5 kg net product; ~99% base oil): Group II 150N (60% ratio @ $1,065/MT = $114.06) + Group II 500N (40% ratio @ $1,205/MT = $86.04) → Blended Base Oil Cost per drum = $136.85.
- Chemical Additive Package (0.85% treat rate; $4,250/MT): ~1.52 kg of specialized ZDDP, antioxidant, anti-foam, and yellow-metal inhibitor chemistry → Additive Cost per drum = $6.46.
- Packaging Hardware (Cold-Rolled SPCC 208L Drum + Internal Phenolic Lining): Certified drum body, bungs, brand screen-printing, anti-corrosion barrier → Packaging Cost per drum = $25.10.
- Compounding, Quality Assurance & Utilities: Isothermal kettle energy, steam generation, nitrogen blanketing, certified laboratory testing (ASTM D445, D2270, D92, D97, D1401) → Processing Cost per drum = $8.65.
- Factory Drayage to Xiamen Port & Terminal Export Clearance: Palletized container stuffing, port terminal handling charges (THC), export customs documentation → Drayage Cost per drum = $5.35.
This establishes an absolute factory manufacturing floor of $182.41 per 208L drum, before commercial financing reserves, container demurrage allowances, and sustainable factory operating margin. With prompt Brent crude stabilizing near $85.00/bbl, finished FOB export quotations must adjust commensurately to maintain factory operational stability and supply continuity.
11. Authoritative 3-Day Multi-Grade Price Trajectory Matrix (FOB Xiamen Export Forecast)
To provide international procurement executives, fleet operators, and lubricant distributors with transparent budgeting visibility, the FOSS Lubrication Research Desk publishes our authoritative 3-day forward price projection matrix. These prices represent verified FOB Xiamen (CNXMN) export prices per 208-liter cold-rolled steel tight-head drum for full-container-load (FCL) bookings (80 drums / 16,640 liters per 20ft container):
Note: All quoted prices represent FOB Xiamen Port (CNXMN) in standard 208L steel drums, based on minimum 1x20ft FCL orders (80 drums). Prices are valid for 30 calendar days from formal Proforma Invoice (PI) countersignature and advance deposit receipt. Prices exclude destination import duties, port-of-entry terminal handling charges, and inland freight at discharge ports.
12. Strategic B2B Buyer Procurement Directives & Financial Hedging Playbook
In an inflationary energy cycle characterized by compounding feedstock, additive, and maritime freight surcharges, passive spot-market purchasing exposes industrial enterprises and regional distributors to severe financial erosion and catastrophic line-stoppage risks. To protect procurement budgets and preserve competitive distribution margins, the FOSS Commercial Strategy Desk recommends the immediate execution of four proactive risk-hedging protocols:
Directive 1: Secure 60-Day Forward Production Allocations via 30-Day Fixed PI Agreements
Primary blending plants like FOSS operate physical hedging mechanisms through advance procurement of virgin base oils and additive masterbatches. By issuing formal purchase orders and executing a standard 30% advance deposit under our 30-Day Fixed Proforma Invoice (PI) program, international buyers freeze the net FOB unit price for all dispatched containers over a 60-day window, insulating their business against spot crude spikes above $85.00/bbl and refinery base stock contract markups.
Directive 2: Consolidate Shipments to Full-Container-Load (FCL) 80-Drum Palletless Configurations
Less-than-container-load (LCL) consolidated ocean freight incurs disproportionately high CFS (Container Freight Station) handling charges, deconsolidation fees, and increased risk of drum handling puncture. Standard 20-foot general-purpose containers (20GP) accommodate exactly 80 drums of 208L lubricants in a two-tier configuration (40 drums bottom tier, solid wooden separator boards, 40 drums top tier) utilizing reinforced dunnage securing. This configuration maximizes container cube utilization to 16,640 liters (approximately 14.8 metric tons net payload), reducing sea freight unit costs by up to $0.08 per liter compared to palletized 64-drum configurations.
Directive 3: Enforce Rigid Pre-Shipment Multi-Point Certificate of Analysis (CoA) Verification
Never accept generic, unverified mill sheets or broker certificates. Mandate that every dispatched container is accompanied by a batch-specific, signed Certificate of Analysis (CoA) from an ISO 9001 certified laboratory verifying: (a) 40°C kinematic viscosity within ±5% of nominal ISO viscosity; (b) Viscosity Index ≥ 98 (for Group II L-HM); (c) Demulsibility separation under 15 minutes (ASTM D1401); (d) Flash point ≥ 220°C (ASTM D92); and (e) Zero particulate sediment or moisture turbidity. FOSS provides pre-shipment retain samples and digital CoA documentation 72 hours prior to vessel departure.
Directive 4: Bypass Intermediary Trading Agents to Partner Directly with Compounding Plants
In volatile trading conditions, trading companies and third-party intermediaries frequently re-negotiate agreed pricing or cancel confirmed contracts when wholesale prices rise before shipment. Working directly with primary manufacturers guarantees operational transparency, priority production queue scheduling, customizable private-label (OEM/ODM) drum screen printing, and uninterrupted access to senior tribological engineering consultation.
13. Factory-Direct Procurement & Technical Consultation Portal
For industrial procurement directors, multinational plant managers, and regional lubricant distributors seeking immediate spot price lock-in, customized formulation blending, or private-label OEM export packaging, contact the FOSS Lubrication Export Operations Desk directly:
- Direct Corporate Email: [email protected]
- Direct WhatsApp Desk: +86 15959543210 (Instant RFQ response within 30 minutes)
- Factory Headquarters: Quanzhou Foss Lubrication Technology Co., Ltd. (泉州市福斯润滑科技有限公司), Quanzhou, Fujian Province, China
- Export Loading Gateways: Xiamen Port (CNXMN) / Quanzhou Port (CNQZ)
Definitive 3-Day Lubricant & Base Oil Trend Forecast
Synthesized by the FOSS Quantitative Energy Modeling Desk based on active shipping line container bookings, regional tank farm draw-down rates, and prompt ICE Brent futures sentiment:
Brent crude consolidates firmly above $84.50; Northeast Asian refiners formalize November contract premiums (+US$15–$20/MT on Group II 500N) amid persistent hydrocracker middle-distillate diversion.
Cape of Good Hope container rerouting and war-risk insurance surcharges fully embedded into chemical logistics; finished anti-wear hydraulic oil export quotes adjust upward by $2.00–$3.00 per 208L drum.
Secondary blenders and sub-tier toll manufacturers face acute replacement margin deficits; international distributors accelerate 60-day inventory bookings under FOSS 30-day fixed-price proforma invoices.
5. Strategic Sourcing & Hedging Directives for Overseas Importers
For overseas procurement directors, fleet operators, and industrial distributors, market volatility represents both operational risk and competitive opportunity. We recommend the following three concrete actions for managing Q4 procurement:
Lock 60-Day Container Requirements
Secure firm proforma invoices (PI) with 30-day price validity. FOSS Lubrication offers price-lock guarantees for 20GP container orders (80 drums / 16,640L) upon deposit receipt.
Audit Laboratory CoA Verification
Demand full pre-shipment ASTM test parameters: kinematic viscosity at 40°C / 100°C, viscosity index ≥ 100, flash point ≥ 220°C, pour point ≤ -15°C, and zero moisture contamination.
FOSS Lubrication: Factory-Direct Precision Engineering
Operating out of Quanzhou, China, FOSS blends over 20,000 MT annually of ISO VG 32/46/68 anti-wear hydraulic oils, CK-4 heavy-duty engine oils, and industrial gear lubricants. Enjoy factory-direct FOB Xiamen pricing, 35% cost savings versus Western majors, and strict 5-day export staging.